
7 Retirement Landmines to Avoid in 2027
and how to plan around them
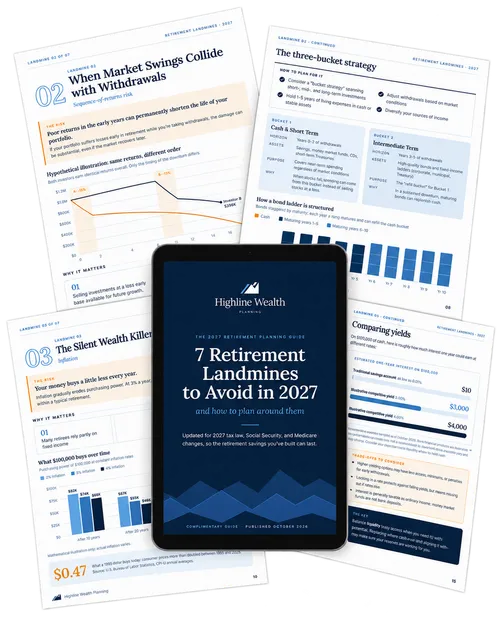
Free 23-page PDF, emailed to you as soon as you sign up.
Seven risks that can quietly derail a retirement plan, and the moves people use to handle each one. Free, 23 pages, updated for 2027.
Inside, you'll see:
Two retirees. Same $1 million, same returns, same withdrawals. Eighteen years later, one has about $396,000 left and the other about $24,000. The only difference is something neither of them could control. See the strategy built for exactly this (page 8).
The two-year look-back on Medicare. Your 2025 income sets your 2027 premiums. Learn why a large withdrawal or Roth conversion this year can show up on a Medicare bill two years from now (page 16).
The $6,000 deduction that disappears after 2028, and the common retirement move that can quietly shrink it.
The cash check most people skip. $100,000 in a 0.01% savings account earns about $10 a year. See what that same cash could earn elsewhere (illustrative).
The giving rules that changed in 2026, including a new deduction for people who don't itemize. Plus how gifts of stock, or gifts from your IRA at 70½, can lower your tax bill.
What inflation does to a 30-year retirement. At 3% a year, $100,000 of income ends up buying what about $41,000 buys today. See why "safe" money carries its own risk.
Why claiming Social Security at 62 can cut your check by up to 30% for life, and the claiming mistake that hits a surviving spouse hardest (page 12).
Plus a quarter-by-quarter 2027 planning calendar with the deadlines that matter, and a ten-question self-check to see which landmines apply to you.
The $1 million example is hypothetical, adapted from the Schwab Center for Financial Research, and does not reflect taxes, fees or actual results. Interest figures use illustrative rates as of October 2026; rates change. The inflation example assumes 3% annual inflation.
Read the first pages before you download
Open any tab below to see real pages from the guide.
The full guide adds Landmines 02 to 07, the 2027 planning calendar and the ten-question self-check.
You've done the saving. The next part has new rules.
Most people plan carefully while they're saving. The years they live off that money get less attention. That's where small choices get expensive: which account to pull from first, when to claim Social Security, how much cash to keep, and when to convert to a Roth.
2027 adds new numbers to every one of those decisions. Social Security benefits rise 3.6% in January. The $6,000 senior deduction runs only through 2028. And the income you report for 2025 is what sets your Medicare premiums for 2027.
Only 35% of Americans who haven't retired yet think their retirement savings are on track. The rest say they're not, or they aren't sure.
Source: Federal Reserve Board, Economic Well-Being of U.S. Households in 2025 (May 2026), Survey of Household Economics and Decisionmaking.
Most retirement guides tell you what to do. This one also shows you what each option costs.
Written for people in or near retirement
This guide is for you if:
- You're retired, or planning to retire in the next several years
- Most of your savings sit in 401(k)s, IRAs and brokerage accounts
- You want to make 2027's tax, Social Security and Medicare decisions on purpose, with the numbers in front of you
It's probably not for you if you're early in your career and still mostly saving. The guide focuses on the years you live off your savings.
Questions
See the 7 landmines before 2027 starts
The rules change in January. See what changes, what it means for your savings, and your options before it does.
Free PDF · 23 pages · 2027 Edition